Best Retirement Plans for Business Owners to Reduce Taxes

A good retirement plan can do two jobs at once: help build long-term wealth and lower the tax bill along the way. For business owners, the difference between “saving something” and choosing the right plan can be significant.
The best choice depends on profit, payroll, number of employees, age, cash flow, and how much administrative work the business can handle. A solo consultant with no employees may need a very different plan than a medical practice, restaurant group, or family-owned company with staff.
This guide breaks down the main retirement plans business owners use to reduce taxable income, what each one is best for, and where the tax savings usually come from.
This article is for general information only and is not tax, legal, or investment advice. Retirement plan rules change, and the right structure depends on your full financial picture.

How retirement plans reduce taxes for business owners
Most tax savings come from deductible contributions. When a business contributes to a qualified retirement plan, those contributions may reduce taxable business income. If the owner contributes as an employee, those deferrals may also reduce personal taxable income.
The basic tax benefits usually fall into three categories:
Current-year tax deductions
Traditional retirement contributions may lower taxable income for the year.
Tax-deferred growth
Investments inside the account can grow without annual tax on interest, dividends, or capital gains.
Potential payroll and employee retention benefits
A strong plan can help attract and keep employees, while still creating owner tax savings.
Roth contributions work differently. They do not usually reduce current taxable income, but qualified withdrawals may be tax-free later. That can still be valuable, especially if the owner expects higher taxes in retirement.
The key is matching the plan to the business. A plan that sounds generous on paper may not work if it requires contributions the company cannot afford. A simple plan may save very little tax if the owner has high income and wants to shelter more.
SEP IRA works well for simple, high-profit solo businesses
A SEP IRA, short for Simplified Employee Pension, is one of the easiest retirement plans for self-employed people and small business owners.
It is popular because it has low administrative burden. There is no annual Form 5500 filing for a standard SEP IRA, and setup is usually simpler than a 401(k). Contributions are made by the employer, not by employees through salary deferrals.
For a sole proprietor, that means the business contributes for the owner. For a company with employees, the employer generally must contribute the same percentage of eligible compensation for eligible employees.
Best fit
A SEP IRA often works well for:
Solo business owners
Independent contractors
Side-business owners with meaningful profit
Businesses with few or no eligible employees
Owners who want flexibility from year to year
Tax advantage
SEP IRA contributions are generally deductible to the business, within IRS limits. The business can choose how much to contribute each year, including nothing in a lean year.
That flexibility is useful for businesses with uneven income. A consultant who earns much more this year than last year can make a larger contribution for the profitable year, then reduce or skip contributions later if revenue drops.
Main drawback
If the business has eligible employees, the contribution cost can rise fast. The same contribution percentage usually applies to employees as to the owner. That can be fair and valuable, but it may not be ideal if the main goal is maximizing the owner’s retirement contribution.
A SEP IRA is simple, but it is not always the most powerful tax-savings tool for an owner who wants to contribute aggressively.
Solo 401(k) is often the top choice for owner-only businesses
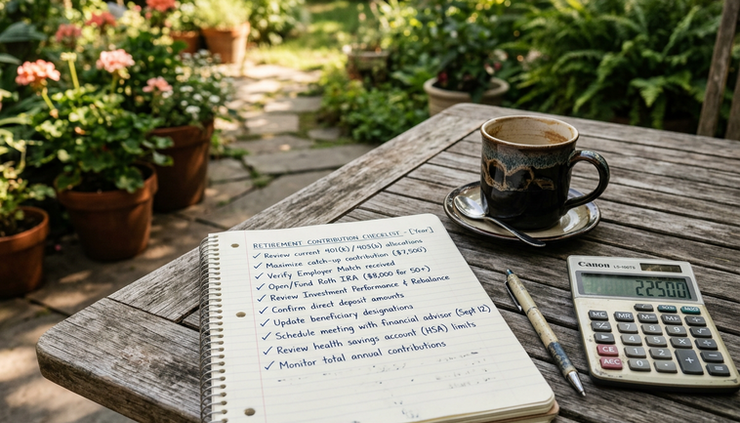
A solo 401(k), also called an individual 401(k), is designed for a business owner with no employees other than a spouse.
It can allow higher contributions than a SEP IRA at the same income level because the owner can contribute in two ways:
As the employee, through salary deferrals
As the employer, through profit-sharing contributions
That combination can make the solo 401(k) especially useful for owners who want to save a large share of income.
Best fit
A solo 401(k) may be a strong option for:
Freelancers with high profit
Single-member LLC owners
S corporation owners with no non-spouse employees
Married couples who work in the same owner-only business
Business owners who want Roth and loan features, if the plan allows them
Tax advantage
Traditional solo 401(k) contributions can reduce taxable income. Employer contributions may reduce business income, while employee deferrals may reduce the owner’s wages or self-employment income for income tax purposes.
Another advantage is control. Many solo 401(k) providers offer both traditional and Roth contribution options. Some plans also allow participant loans, though borrowing from retirement savings should be handled carefully.
Main drawback
Solo 401(k)s have more rules than SEP IRAs. Once plan assets pass certain thresholds, annual IRS filing may be required. The plan also must be operated correctly, with attention to deadlines, compensation limits, and contribution calculations.
The biggest limitation is eligibility. If the business hires eligible employees, the owner may need to convert to a regular 401(k) or choose another plan design.
SIMPLE IRA is a practical option for small teams
A SIMPLE IRA, short for Savings Incentive Match Plan for Employees, is built for small businesses that want an employee retirement plan without the complexity of a traditional 401(k).
Employees can contribute through salary deferrals, and the employer makes either matching or nonelective contributions, depending on the plan structure.
Best fit
A SIMPLE IRA can work well for:
Small businesses with employees
Owners who want easier administration
Companies that are not ready for a full 401(k)
Businesses that want employees to share in retirement saving
Tax advantage
Employer contributions are generally deductible. Employee salary deferrals are usually made before income tax, unless Roth SIMPLE features are available and selected.
For an owner with employees, a SIMPLE IRA can provide tax savings while creating a retirement benefit for the team. It is often easier and less expensive to run than a 401(k).
Main drawback
Contribution limits are lower than many 401(k) options. That means a SIMPLE IRA may not be enough for a high-income owner who wants to reduce a large tax bill.
There are also rules around employer contributions and plan timing. Once the plan is in place, the company must follow the chosen contribution formula.
A SIMPLE IRA is a solid middle ground, but it may not be the best fit for maximum owner tax sheltering.
Traditional 401(k) gives growing businesses more design control
A traditional 401(k) can be one of the most flexible retirement plans for a business with employees. It has more administration than SEP and SIMPLE plans, but it also offers more ways to shape contributions.
A 401(k) plan can include employee deferrals, employer matching, profit-sharing contributions, Roth options, automatic enrollment, and vesting schedules. With the right design, it can support both employee benefits and owner tax planning.
Best fit
A traditional 401(k) may suit:
Businesses with several employees
Companies with steady cash flow
Owners who want higher contribution potential
Firms competing for talent
Businesses that want plan design flexibility
Tax advantage
Employer contributions are generally deductible. Traditional employee deferrals reduce taxable wages for employees, including owner-employees. Profit-sharing contributions may also allow the business to make larger deductible contributions in profitable years.
A well-designed 401(k) can help business owners save more than they could through a SIMPLE IRA, especially when combined with profit-sharing.
Main drawback
A 401(k) comes with legal, administrative, and testing requirements. Plans often need nondiscrimination testing to make sure they do not unfairly favor owners and highly compensated employees.
The business may need a third-party administrator, recordkeeper, investment platform, and advisor. Costs can be worthwhile, but they should be measured against the expected tax savings and employee benefit value.

Safe harbor 401(k) can help owners contribute more
A safe harbor 401(k) is a type of 401(k) plan that can avoid certain annual nondiscrimination tests if the employer makes required contributions to employees.
That can be valuable when owners or high earners want to contribute the maximum salary deferral amount, but rank-and-file employees contribute at low rates.
Best fit
A safe harbor 401(k) is often useful for:
Businesses where owners want to maximize deferrals
Companies with lower employee participation
Firms that can commit to required employer contributions
Owners who want fewer testing problems
Tax advantage
The owner may be able to make larger salary deferrals without being limited by failed testing. Employer safe harbor contributions are generally deductible, subject to the rules.
This can make the safe harbor design more predictable than a standard 401(k). The tradeoff is that the employer must fund the required contributions.
Main drawback
Safe harbor plans are less flexible than some business owners expect. Required contributions must follow plan rules, and notices or deadlines may apply.
For businesses with many employees, the mandatory contribution cost can be meaningful. For profitable firms, though, that cost may be acceptable because it supports larger owner contributions and better employee benefits.
Cash balance plans can create large deductions for high-income owners
A cash balance plan is a type of defined benefit pension plan. It is more complex than a 401(k), but it can allow much larger tax-deductible contributions, especially for older, high-income business owners.
Instead of only defining what goes into the plan, a cash balance plan defines a promised benefit. Contributions are calculated by an actuary based on factors such as age, income, plan design, and expected investment returns.
Best fit
Cash balance plans often work best for:
High-income business owners
Professional practices
Owners in their 40s, 50s, or 60s
Businesses with stable profits
Companies already funding a 401(k) or profit-sharing plan
Examples include medical groups, law firms, engineering firms, consulting companies, and profitable closely held businesses.
Tax advantage
The biggest appeal is contribution size. A cash balance plan can sometimes allow much larger deductible contributions than a defined contribution plan alone.
For an owner nearing retirement with high taxable income, that can create meaningful tax savings while accelerating retirement funding.
Main drawback
Cash balance plans require commitment. They involve actuarial calculations, required funding rules, higher administrative costs, and long-term obligations. They are not ideal for businesses with unpredictable cash flow.
They also need careful design when employees are involved. The business may need to make contributions for eligible staff, not just owners.
For the right business, a cash balance plan can be one of the most powerful tax-reduction tools available. For the wrong business, it can feel too rigid.
Profit-sharing plans add flexibility to a 401(k)
A profit-sharing plan is often added to a 401(k), rather than used alone. Despite the name, the business does not always need formal profit to make contributions, but contributions must follow plan rules.
This feature lets the employer make discretionary contributions to employee accounts. Some designs allow different contribution rates for different employee groups, as long as nondiscrimination rules are satisfied.
Best fit
Profit-sharing can work well for:
Businesses with variable profits
Owners who want flexible employer contributions
Companies with a 401(k) plan already in place
Firms seeking higher total retirement contributions
Tax advantage
Employer profit-sharing contributions are generally deductible. For owner-employees, this can increase total retirement savings beyond salary deferrals alone.
A common setup is a 401(k) with safe harbor contributions plus profit-sharing. In some cases, this design gives owners a clearer path to higher annual contributions while keeping the plan compliant.
Main drawback
Plan design matters a lot. Poor design can force the business to make larger employee contributions than expected or limit owner benefits.
This is where a qualified plan administrator or retirement plan advisor becomes valuable. The right formula can make a major difference.
Defined benefit pension plans are powerful but demanding
Traditional defined benefit plans are less common than 401(k)s, but they can still make sense for some owners. Like cash balance plans, they promise a future retirement benefit and require actuarial funding.
These plans can allow large deductions, especially for older owners who need to catch up on retirement savings.
Best fit
A defined benefit plan may be useful for:
Very high-income owners
Owners close to retirement
Businesses with consistent profits
Small firms with few employees
Owners who want predictable pension-style benefits
Tax advantage
Contributions are generally deductible and may be much higher than those allowed in many defined contribution plans.
Main drawback
The plan must be funded according to actuarial rules. If business income drops, required contributions can become stressful. Administration is also more expensive and complex than most small business plans.
For that reason, many owners who like the idea of a pension look first at cash balance plans, which can feel more understandable while still offering large contribution potential.

How to choose the right plan
The best plan starts with a few practical questions.
Do you have employees?
If there are no employees other than a spouse, a solo 401(k) or SEP IRA may be enough.
If there are employees, the plan must account for eligibility, required contributions, testing, and employee communication. A SIMPLE IRA, safe harbor 401(k), or traditional 401(k) may fit better.
How much do you want to contribute?
If the goal is moderate saving with low paperwork, a SEP IRA or SIMPLE IRA may work.
If the goal is to save as much as possible, look at a solo 401(k), 401(k) with profit-sharing, or cash balance plan.
How steady is your income?
Variable income favors flexible plans. SEP IRAs and profit-sharing features can be useful because contributions may change from year to year.
Stable high income can support more advanced plans, including safe harbor 401(k)s and cash balance plans.
How close are you to retirement?
Older owners may benefit more from cash balance or defined benefit plans because contribution calculations often allow larger amounts as retirement age approaches.
Younger owners may prefer flexible plans with Roth options, lower costs, and long investment time horizons.
How much administration can the business handle?
Simple plans save paperwork. More advanced plans may save more tax, but they need proper setup and maintenance.
A plan that is ignored after setup can create compliance problems. Choose something the business can actually run well.
Quick comparison of common business retirement plans
Plan | Best for | Tax-saving potential | Complexity |
SEP IRA | Solo owners or very small firms | Medium to high | Low |
Solo 401(k) | Owner-only businesses | High | Medium |
SIMPLE IRA | Small businesses with employees | Medium | Low to medium |
Traditional 401(k) | Growing companies | High | Medium to high |
Safe harbor 401(k) | Owners wanting max deferrals | High | Medium to high |
Cash balance plan | High-income owners | Very high | High |
Defined benefit plan | Older high-income owners | Very high | High |
Common mistakes that reduce tax benefits
The plan choice matters, but execution matters just as much. Watch for these common problems:
Missing setup or contribution deadlines
Forgetting required employee contributions
Choosing a SEP IRA without considering employee cost
Using a SIMPLE IRA when contribution goals are much higher
Adding a 401(k) but failing compliance testing
Not coordinating retirement contributions with S corporation wages
Ignoring state tax treatment
Waiting until after year-end to ask about advanced plan options
Business owners often think about retirement plans in December, when the tax bill becomes clear. That can be too late for some strategies. Planning earlier in the year gives more room to choose the right structure.
The best choice for most business owners
There is no single winner for every business, but some patterns are clear.
For an owner-only business, the solo 401(k) is often the most powerful mix of tax savings, flexibility, and contribution potential.
For a simple solo business that wants low maintenance, a SEP IRA can be a smart choice.
For a small business with employees that wants an easy starting point, a SIMPLE IRA may work well.
For a profitable business that wants stronger owner contributions and employee benefits, a safe harbor 401(k) with profit-sharing is often worth reviewing.
For high-income owners with steady profits, especially those closer to retirement, a cash balance plan may offer the largest deductions.
The right retirement plan should fit the business, not just the tax goal. A good plan reduces taxes, supports retirement, treats employees properly, and remains manageable year after year. Start with your income, payroll, age, and savings target, then have a tax professional and retirement plan specialist model the options before choosing.

Comments